Retail credit card

Manage your retail card online

Make payments, set alerts, and view statements from virtually anywhere.

Get the app


Enroll now

‍

Get to know your retail card

Special financing

Know more about the terms of each financing promotion and what they mean for you.
Find out more

Billing statement

Check out a sample to understand your statement and set preferences to paperless.
See sample statement

Credit card agreement

Review credit card agreements to understand key information such as rates, fees, and terms.

View agreement

‍

How your special financing works

No interest if paid in full

[Music]

[On-Screen Title Text]

Understanding

“No interest if paid in full”

[Narrator Voiceover]

Every now and then I've used special financing to cover a big purchase. Taking advantage of a credit card that offered no interest if paid in full financing made sense.

[On-Screen Visual]

Icons numbered 1, 2, and 3 animate across with the following:

[On-screen Text]

Applied

Approved

Purchased

[Narrator Voiceover]

I've applied, been approved, and completed my purchase. Plus, the payment options were surprisingly reasonable.

[On-Screen Visual]

A row of icons animate across in sequence: Shopping icon, Interest Terms icon, Clock icon, Cash icon, Calendar icon, Trophy icon with the following text for each:

[On-screen Text]

Purchase day

Interest starts accruing

Time passes

Pay in full

Promo period

Accrued interest is waived [with a green check]

[Narrator Voiceover]

I knew going into it that I'd start accruing interest the day I made my purchase. But I also knew if I repaid my balance within the promotional period, I wouldn't have to pay the accrued interest.

[On-Screen Title Text]

Why pay interest if you don't have to?

[Narrator Voiceover]

Why pay interest if you don't have to?

[On-Screen Text]

$1,200 divided by 12 months = $100 Monthly Payment

[Narrator Voiceover]

Knowing that minimum payments might not pay off the balance in time, I took what I borrowed and divided it by the number of months in my promotional period.

[On-Screen Visual]

A grid of 12 Cash icons builds on

[On-Screen Text]

12 Equal $100 Monthly Payments

No Interest $0 Account Balance

[Narrator Voiceover]

If I paid this much on time every month, barring additional purchases, I knew I would pay off the balance before the accrued interest is charged,

[On-Screen Visual]

A single Cash icon is scaled up from the grid for emphasis

[On-Screen Text]

11 Minimum Monthly Payments + Remaining Balance in Month 12

[Narrator Voiceover]

or I could pay the minimum payment due on the statement. But just paying the minimum each month will leave a large amount due at the end of the promotional period.

[On-Screen Title Text]

What happens if you don't pay off the balance by the end of the promotional period?

[Narrator Voiceover]

What happens if you don't pay off the balance by the end of the promotional period?

[On-Screen Visual]

Calculator icon, Interest Terms icon, and Currency icon animate across as an equation with the text:

[On-Screen Text]

Remaining Balance $200

+ Accrued Interest $270

= Current Obligation $470

[Narrator Voiceover]

Things get expensive. You're still responsible for the unpaid balance, and now you'll have to pay the interest that's been accruing since the purchase date, and that amount will continue to accrue interest until you pay your balance in full.

[On-Screen Visual]

Light Bulb icon

[On-Screen Text]

Key takeaway: Pay off your balance in full by the end of the promotional period to avoid paying interest.

[Narrator Voiceover]

Key takeaway. Pay off your balance in full by the end of the promotional period to avoid paying interest.

[On-Screen Visual]

Monthly Statement icon

[On-Screen Text]

Monthly Statement

[Narrator Voiceover]

Make sure to pay at least the minimum payment on time every month.

[On-Screen Visual]

Warning icon

[On-Screen Text]

Late Fees

[Narrator Voiceover]

Late or missed payments incur a late fee,

[On-Screen Visual]

Interest Terms icon

[On-Screen Text]

Accrued Interest

[Narrator Voiceover]

which will accrue interest at the regular interest rate if it's not paid by the next payment due date.

[On-Screen Visual]

Laptop icon

[On-Screen Text]

wellsfargo.com/cardholders

[Narrator Voiceover]

Signing up for automatic payments and payment alerts through Wells Fargo online can help you avoid missing a payment or paying late.

[On-Screen Visual]

Laptop icon falls back and animates across with Mobile icon, Mouse Click icon, and Mail icon

[Narrator Voiceover]

You can always pay by phone, online, or through the mail.

[On-Screen Visual]

Billing icon, Settings icon, and Calendar icon animate across

[Narrator Voiceover]

Use your monthly billing statements to check your progress and remaining promotional balance to avoid accrued interest charges. When making financial decisions, it's always good to be informed.

[On-Screen Text]

Thank you!

[Narrator Voiceover]

Thank you for making the time to learn how a No Interest If Paid In Full promotion works.

[On-Screen Visual]

The Wells Fargo Logo appears

[On-Screen Text]

WELLS FARGO

wellsfargo.com/cardholders

© 2026 Wells Fargo Bank, N.A.

[On-Screen Text]

NO INTEREST IF PAID IN FULL

This special terms plan is also referred to within the industry as “Deferred Interest” plans. Key attributes

of this plan include the following:

The Annual Percentage Rate (“APR”) for Purchases is used to calculate interest on the purchase balance from the date of the original transaction and throughout the special terms (promotional) period. This amount is called the deferred interest charge.

To avoid paying any interest, a Cardholder must pay off the entire purchase balance in full on or before the special terms end date.

If the Cardholder does not pay off the purchase balance by the end of the special terms period, the deferred interest from the date of the original transaction will be added to the remaining balance, and the APR for Purchases will continue to apply until the purchase balance is paid in full.

Paying only the minimum payment amount each month will not pay off the No Interest if Paid in Full purchase balance during the special terms period.

Monthly payments must be made each month. The revolving account may not be paid ahead. However, the No Interest if Paid in Full purchase balance can be paid by larger monthly payments or by one large payment which we receive on or before the special terms end date.

The special terms end date may be different than the Cardholder’s payment due date.

[On-Screen Text]

APPLICATION OF PAYMENTS

We apply payment amounts equal to or less than the Minimum Payment Due at our discretion. We apply any payment amounts in excess of the Minimum Payment Due as follows:

  • First, to balances with No Interest if Paid in Full terms during the two full Billing Cycles immediately preceding expiration of the special terms period. Otherwise, for purposes of this section only, these balances are considered to have an APR of 0%;
  • Then to balances with higher APRs before lower APRs.

Any payment in excess of the Minimum Payment Due is applied based on the balances reflected on your last statement. We post payments in the Billing Cycle they are received.

Duration: 2 minutes 14 seconds

0% APR with equal payments

[Music]

[On-Screen Title Text]

Understanding “0% APR with equal payments”

[Narrator Voiceover]

Every now and then I've used special financing to cover a big purchase. Taking advantage of a credit card that offered 0% APR financing made sense.

[On-Screen Visual]

Icons numbered 1, 2, and 3 animate across with the following:

[On-screen Text]

Applied

Approved

Purchased

[Narrator Voiceover]

I've applied, been approved, and completed my purchase. Plus, the payment options were surprisingly reasonable.

[On-Screen Visual]

Credit card icon, Terms icon, Payment icon animate across in sequence

[Narrator Voiceover]

Not only did I get the credit that I needed to make the purchase, but I could avoid borrowing costs by sticking to the payment schedule. First, I had to make sure I could afford the monthly payments

[On-Screen Text]

$3,600 divided by 36 months

0% APR with Equal Payments

=$100 Monthly Payment

[Narrator Voiceover]

by taking the amount I wanted to borrow, $3,600, and dividing it by the number of months in the promotional period. In my case, 36 months meant that my monthly payment would be $100, an amount I could afford. So I applied.

[On-Screen Visual]

An array of Money icons spreads across the screen in a rectangle formation

[On-Screen Text]

36 EQUAL

$100 Monthly Payments

$0 Account Balance

[Narrator Voiceover]

Once you commit, you must make your minimum monthly payment every month until the balance is 100% repaid. Keep in mind that you can pay off your balance at any time without penalty.

[On-Screen Visual]

Credit card icon

[Narrator Voiceover]

My credit card arrived about a week after being approved and making the purchase.

[On-Screen Visual]

Monthly Billing icon

[On-Screen Text]

$3600 balance

0% APR with equal payments

Available credit: $1,400

[Narrator Voiceover]

When my monthly billing statement arrived, it reflected what I had borrowed and the available credit left on my credit line.

[On-Screen Title Text]

What happens if you don't make at least your minimum monthly payment on time?

[Narrator Voiceover]

What happens if you don't make at least your minimum monthly payment on time?

[On-Screen Visual]

Monthly Billing icon and Warning icon animate across

[On-Screen Text]

Monthly Statement

Late Fees

[Narrator Voiceover]

If you pay late or fail to make your minimum payment, you'll be charged the late fee.

[On-Screen Visual]

Monthly Payment icon and Warning icon stack in a list

[On-Screen Text]

Monthly Statement    $100

Late Fees (Example)    $29

Regular Interest Rate    +

Current Obligation    $129
[Narrator Voiceover]
Plus, the regular interest rate will be charged on any late fee that's not paid by the next payment due date. So make sure you pay both the minimum amount due and any fees that are due on the account.

[On-Screen Visual]

Light Bulb icon

[On-Screen Text]

Key Takeaway: Make at least your minimum payment on time every time to avoid a late fee.

[Narrator Voiceover]

Key takeaway. Make at least your minimum payment on time, every time, to avoid a late fee.

[On-Screen Visual]

Laptop icon

[On-Screen Text]

wellsfargo.com/cardholders

[Narrator Voiceover]

Signing up for automatic payments and payment alerts through Wells Fargo online can help you avoid missing a payment or paying late.

[On-Screen Visual]

Laptop icon falls back and animates across with Mobile icon, Mouse Click icon, and Mail icon

[Narrator Voiceover]

You can always pay by phone, online, or through the mail.

[On-Screen Visual]

Billing icon, Settings icon, and Calendar icon animate across

[Narrator Voiceover]

Use your billing statements to check your progress and avoid surprises.

[On-Screen Visual]

Credit Card icon, Shopping icon, and Chat icon animate across

[On-Screen Text]

Purchases made with your card will be at the regular rate unless special financing terms are available.

[Narrator Voiceover]

You can continue to use your available credit to make new purchases with your card. Be sure to ask about current financing promotions available. Purchases made with your card will be at the regular rate unless special financing terms are available. When making financial decisions, it's always good to be informed.

[On-Screen Text]

Thank you!

[Narrator Voiceover]

Thank you for making the time to learn how a 0% APR promotion works.

[On-Screen Visual]

The Wells Fargo Logo appears

[On-Screen Text]

WELLS FARGO

wellsfargo.com/cardholders

© 2026 Wells Fargo Bank, N.A.

[On-Screen Text]

0% APR WITH EQUAL PAYMENTS

Special Rate. A special rate of 0% APR may be advertised as a "no interest" special terms promotion. Key attributes of this plan include the following. The 0% APR will apply on the purchase balance from the date of the original transaction until the purchase balance is paid in full.

Payment in Full/Equal Payments. The payment will be the amount required to pay the initial purchase balance shown on the Cardholder's monthly billing statement in full during the special terms period. Because of rounding, the final payment could be less than other payments.

Duration: 2 minutes 16 seconds

Special rate financing

[Music]

[On-Screen Title Text]

Understanding

“Special rate financing”

[Narrator Voiceover]

Every now and then I've used special financing to cover a big purchase. Taking advantage of a credit card that offered special rate financing made sense.

[On-Screen Visual]

Icons numbered 1, 2, and 3 animate across with the following:

[On-screen Text]

Applied

Approved

Purchased

[Narrator Voiceover]

I've applied, been approved, and completed my purchase. Plus, the payment options were surprisingly reasonable.

[On-Screen Visual]

Credit card icon, Currency icon, and Calendar icon animate across in sequence

[Narrator Voiceover]

Not only did I get the credit that I needed for my purchase, but I could keep my borrowing costs low by consistently paying on time or paying off the balance early.

[On-Screen Text]

Minimum Monthly Payments x XX Months = Total Amount Borrowed

[Narrator Voiceover]

By applying, your agreeing to repay a portion of what was borrowed every month with interest until it's paid off.

[On-Screen Text]

Bigger Monthly Payments x XX Months = Shorter Payback Period

[Narrator Voiceover]

Paying more than the minimum every month can help you pay off the balance faster, and you can pay the remaining balance in full anytime you like.

[On-Screen Visual]

Credit card icon

[On-Screen Text]

$6,000 balance

Special Rate Financing

Available credit: $3,000

[Narrator Voiceover]

My credit card arrived about a week after being approved and making the purchase. When my monthly billing statement arrived, it reflected what I had borrowed and the available credit left on my credit line.

[On-Screen Title Text]

What happens if you don't make at least your minimum monthly payment on time?

[Narrator Voiceover]

What happens if you don't make at least your minimum monthly payment on time?

[On-Screen Visual]

Monthly Billing icon and Warning icon animate across

[On-Screen Text]

Monthly Statement

Late Fees

[Narrator Voiceover]

If you pay late or fail to make your minimum payment, you'll be charged the late fee.

[On-Screen Visual]

Monthly Payment icon and Warning icon animate across

[On-Screen Text]

Monthly Statement

Late Fees

[Narrator Voiceover]

Plus, the regular interest rate will be charged on any late fee that's not paid by the next payment due date.

[On-Screen Visual]

Calendar icon

[On-Screen Visual]

Paying icon, Billing icon, and Settings icon animate across

[Narrator Voiceover]

So make sure you pay both the minimum amount due and any fees that are due on the account. Use your billing statements to check your progress and avoid surprises.

[On-Screen Visual]

Credit Card icon, Shopping icon, and Chat icon animate across

[On-Screen Text]

Purchases made with your card will be at the regular rate unless special financing terms are available.

[Narrator Voiceover]

You can continue to use your available credit to make new purchases with your card. Be sure to ask about current financing promotions available. Purchases made with your card will be at the regular rate unless special financing terms are available.

[On-Screen Visual]

Laptop icon

[On-Screen Text]

wellsfargo.com/cardholders

[Narrator Voiceover]

Signing up for automatic payments and payment alerts through Wells Fargo online can help you avoid missing a payment or paying late.

[On-Screen Visual]

Laptop icon falls back and animates across with Mobile icon, Mouse Click icon, and Mail icon

[Narrator Voiceover]

You can always pay by phone, online, or through the mail. When making financial decisions, it's always good to be informed.

[On-Screen Text]

Thank you!

[Narrator Voiceover]

Thank you for making the time to learn how Special Rate Financing works.

[On-Screen Visual]

The Wells Fargo Logo appears

[On-Screen Text]

WELLS FARGO

wellsfargo.com/cardholders

© 2026 Wells Fargo Bank, N.A.

[On-Screen Text]

SPECIAL RATE

Special Rate. This special terms plan is also referred to as "Reduced Rate" plans. Key attributes of this plan includes the following:

The APR shown on the Invoice will be used to calculate interest on the purchase balance from the date of the original transaction and will apply until the purchase is paid in full. Special Rate plans begin as low as 0.00% APR.

Payment in Full/Equal Payments. The payments will be the amount required to pay the initial purchase balance shown on the Cardholder's monthly billing statement in full during the special terms period.

Custom Payments. The payment is a set dollar amount or a fraction (e.g., 1/30, 1/40, etc.) or percent (e.g., 2.00%, 3.00%, etc.) of the highest balance for the particular credit promotion. The payment will not change unless the balance increases above the previous high balance.

Duration: 2 minutes 0 seconds

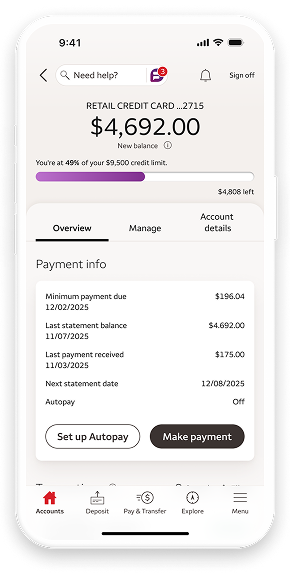
Get the app loved by millions

11M ratings | 4.9 stars**
‍

Explore special offers

Tempur-Pedic
Free delivery. 90 night trial. Plus get $300 in free accessories with any mattress set purchase. Use promo code: 300WELLS

See offer details >

Window World
When quality and value matter most, choose Window World. Special financing options available, with approved credit.

See offer details >

El Dorado Furniture
Shop new arrivals at First Look Pricing! Enjoy flexible financing made for you, with approved credit.

See offer details >

‍

Contact information

For help with your card, contact us

1-877-805-7744
Monday through Friday
8:00 am to 6:00 pm, Central Time

For questions about your card

Sign-up may be required. Availability may be affected by your mobile carrier's coverage area. Your mobile carrier's message and data rates may apply.

Terms and conditions apply. Setup is required for transfers to and/or from other U.S. financial institutions, and verification may take 1–3 business days. Customers should refer to their other U.S. financial institutions for information about any potential fees charged by those institutions. Mobile carrier’s message and data rates may apply. See Wells Fargo’s Online Access Agreement for more information.

Online Statements require Adobe® Acrobat® PDF reader. For credit card accounts, Online Statements are available to view and download for up to 2 years. Availability may be affected by your mobile carrier’s coverage area. Your mobile carrier’s message and data rates may apply.

Availability may be affected by your mobile carrier's coverage area. Your mobile carrier's message and data rates may apply.

You must be a Wells Fargo account holder of an eligible Wells Fargo consumer account with a FICO® Score available, and enrolled in Wells Fargo Online®. Eligible Wells Fargo consumer accounts include deposit, loan, and credit accounts, but other consumer accounts may also be eligible. Contact Wells Fargo for details. Availability may be affected by your mobile carrier's coverage area. Your mobile carrier's message and data rates may apply. 

Please note that the score provided under this service is for educational purposes and may not be the score used by Wells Fargo to make credit decisions. Wells Fargo looks at many factors to determine your credit options; therefore, a specific FICO® Score or Wells Fargo credit rating does not guarantee a specific loan rate, approval of a loan, or an upgrade on a credit card.

Wells Fargo and Fair Isaac are not credit repair organizations as defined under federal and state law, including the Credit Repair Organizations Act. Wells Fargo and Fair Isaac don’t provide credit repair services or advice or assistance with rebuilding or improving your credit record, credit history, or credit rating.

Subject to available credit. Ask for details.

Apple, the Apple logo, Apple Pay, Apple Watch, Face ID, iCloud Keychain, iPad, iPad Pro, iPhone, iTunes, Mac, Safari, and Touch ID are trademarks of Apple Inc., registered in the U.S. and other countries. Apple Wallet is a trademark of Apple Inc. App Store is a service mark of Apple Inc.

Android, Google Play, Chrome, Pixel and other marks are trademarks of Google LLC.

FICO is a registered trademark of Fair Isaac Corporation in the United States and other countries.


DT1-07022027-12-8975547-1.1