Retail credit card statement
How to read a retail credit card statement
Review this sample statement to help you understand balances, minimum payments, promotional terms, and interest charges.
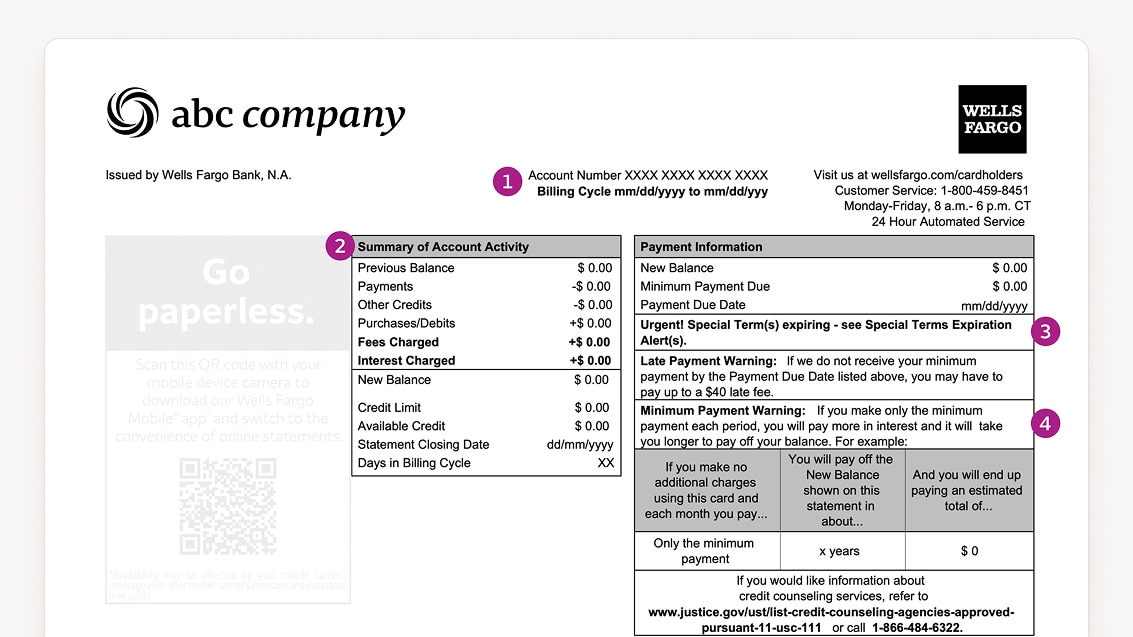
1. Account Information
The 16 digits at the top is your unique account number and the billing cycle is the time period that the statement covers. Each statement has its own billing cycle, which includes all charges, payments, and fees that occurred during that time frame.
2. Summary of Account Activity
This reflects all account activity during the billing cycle, including any payments, purchases, interest or fees, and total balance due.
3. Special Term(s) Expiring
This is a warning message that appears one month before the promotion expires to pay the balance off in full before the expiration date. This box will display the special terms end date on every billing statement for the full duration of the promotion for your convenience.
Note: This section only applies to customers who signed up for the No Interest if Paid in Full special rate financing on the date of purchase (see #7 for more information about your special term calculation).
4. Minimum Payment Warning
The Minimum Payment Warning shows how long it will take to pay off your balance if you make only the minimum payment each month. The table shows how long it would take to pay off the balance with only minimum payments.
Reminder: For customers with No Interest if Paid in Full promotion(s), the table shows how much must be paid each month to pay off the promotional balance on time.
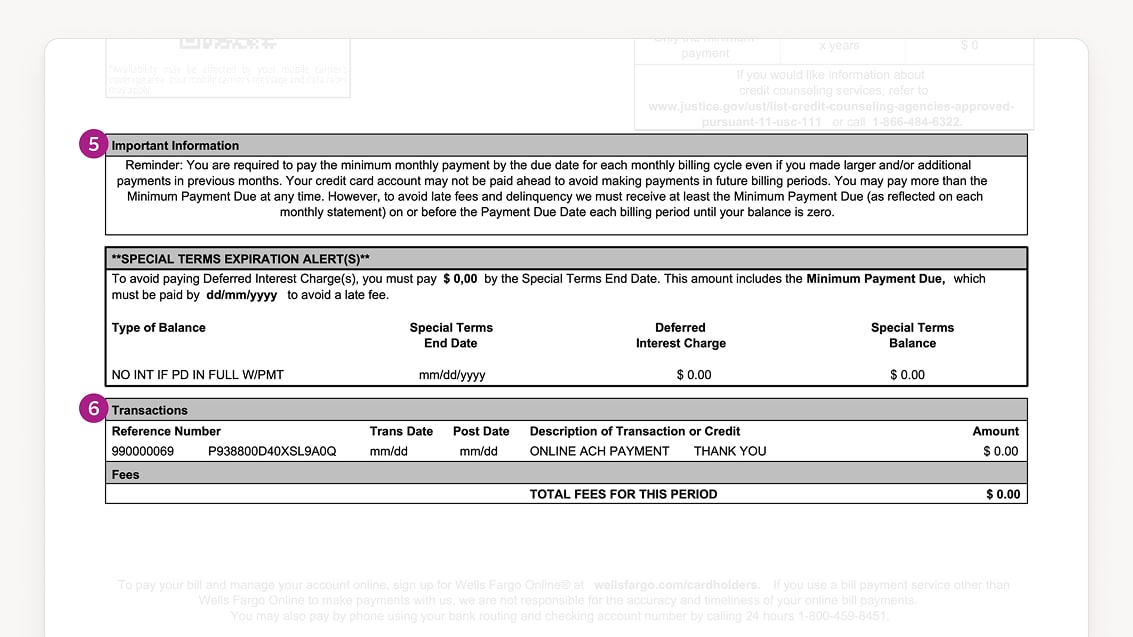
5. Important Information
You can find alerts, changes to your account, and other informational messages printed here.
6. Transaction Summary
You can review all transaction activity (purchases, payments, etc.) listed in order of transaction date. This section includes totals for fees and interest charged this billing cycle and year-to-date.
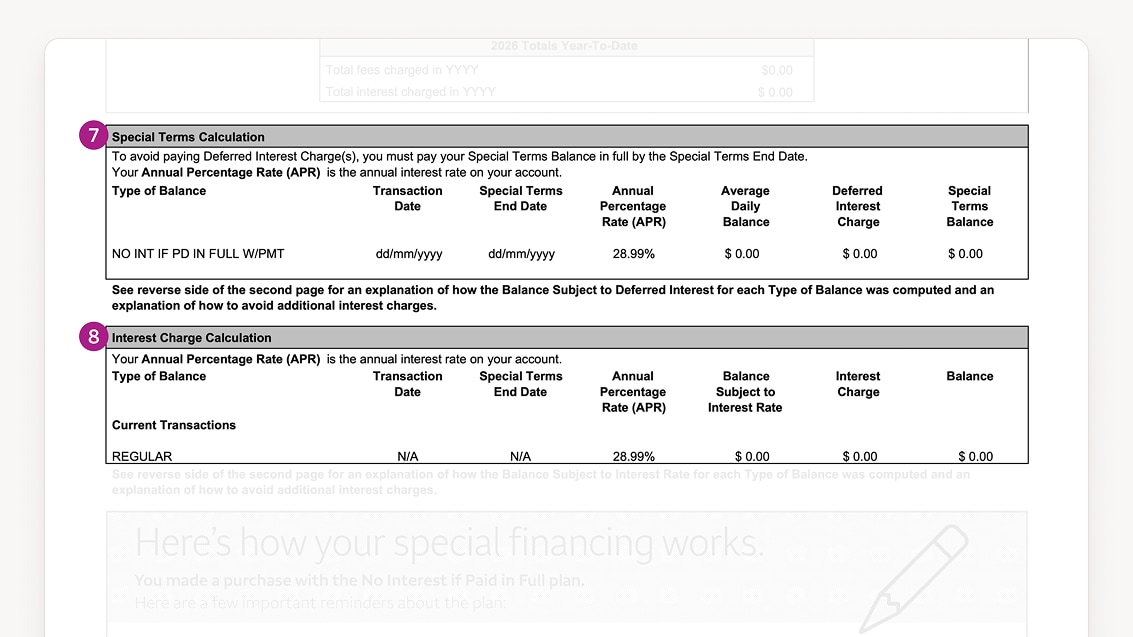
7. Special Terms Calculation
If you receive this message on your billing statement, it’s alerting you that your special terms promotion(s) will expire. For example, if you have a No Interest if Paid in Full promotion, even though you’re not paying interest on your promotional purchase balance during this period, interest is still accruing on that balance.
If you don’t pay off your No Interest if Paid in Full balance(s) in full by the Special Terms End Date(s), you will be responsible paying for the full balance plus the deferred interest (the interest that has been accruing since the date of purchase).
8. Interest Charge Calculation
This section shows your balance(s) by type (i.e., regular, special rate, etc.) with corresponding balance and interest charge for each billing period.
Important points to note
- Special Terms End Date – Important date to remember! You will be required to pay your full balance plus the interest accrued if you fail to pay off the balance in full before the end of the promotional period.
- Deferred Interest Charge – This is the amount of interest that has accrued for No Interest if Paid in Full balances from the original purchase date to this billing cycle.
- Annual Percentage Rate (APR) – This is the annual percentage rate used to calculate the Interest Charge for each type of balance.
If you’re having trouble understanding your promotional terms, refer to this visual guide.
Sign on to Wells Fargo Online® and select your account to view details and then go to View Statements. If you aren’t enrolled in Wells Fargo Online, enroll now.
Contact information
How was your experience? Give us feedback.
DT1-07092027-12-9016449-1.1
